The Gamma and Chi-Square Distributions
STA 211 · Lecture 15
Introduction
The gamma family models positive, right-skewed quantities such as waiting times, lifetimes and aggregate durations. The exponential distribution is a gamma special case, while the chi-square distribution is a re-parameterised gamma distribution central to inference about variances.
Learning Objectives
You should be able to:
- define and use the gamma function;
- state the gamma density under a clear parameterisation;
- calculate gamma probabilities, means, variances and MGFs;
- explain exponential and chi-square special cases; and
- use additivity within the gamma family.
Gamma Function
For ,
The recurrence relation is
For positive integers ,
Also,
Gamma Distribution: Shape-Rate Form
This course uses the shape-rate parameterisation. If , where is the shape and is the rate, then
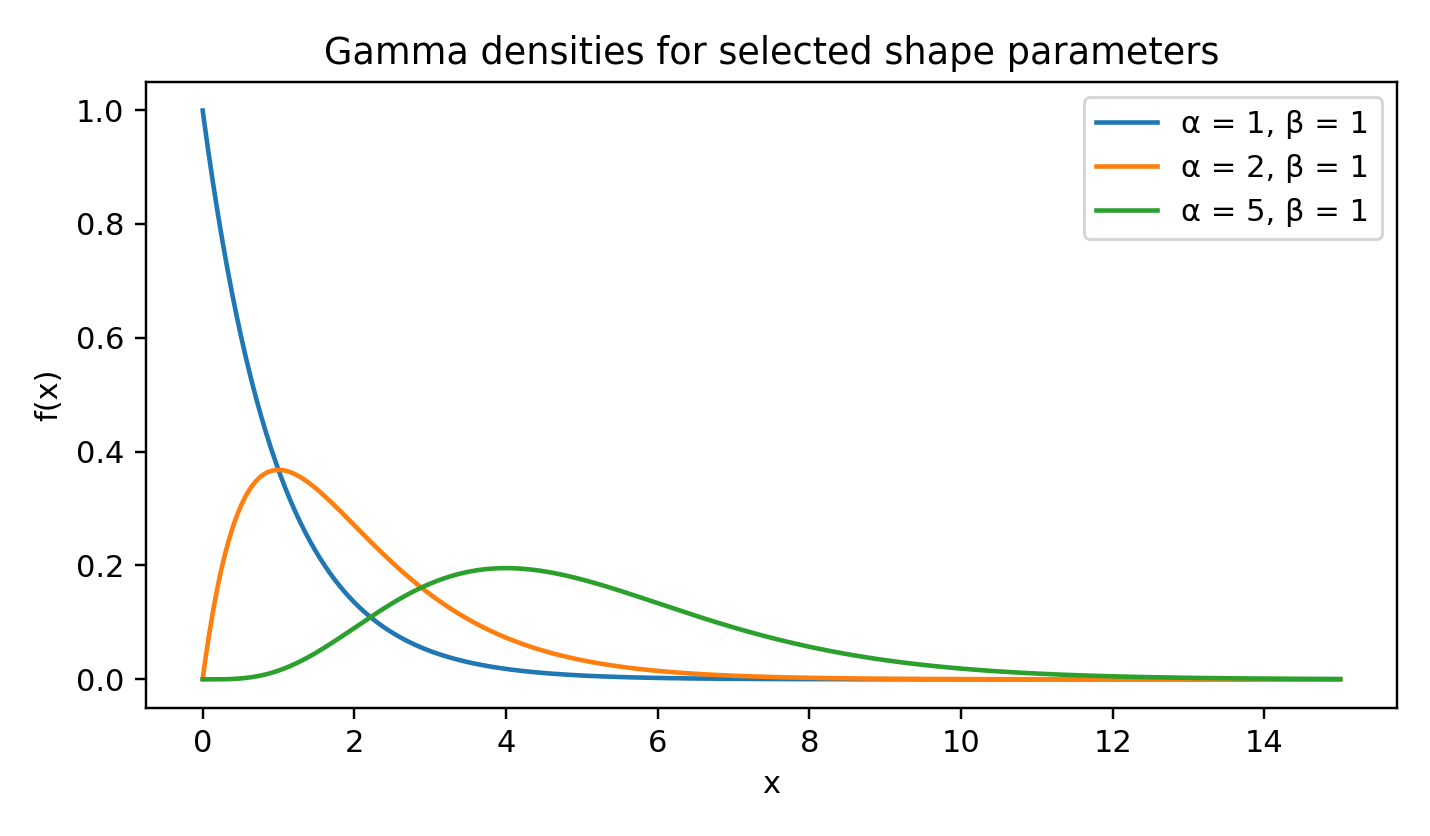
Gamma probability density functions
The mean and variance are
The MGF is
Shape-scale notation
Some texts use scale . Then
The two parameterisations must not be mixed.
Exponential Distribution
When ,
which is the exponential distribution with rate . Its survival function is
Like the geometric distribution, the exponential distribution is memoryless:
Additivity
If are independent with a common rate , then
A common rate is required.
Example 15.1
If independent service stages have distributions and , their total time has distribution
Its mean is and variance is .
Chi-Square Distribution
A chi-square variable with degrees of freedom is a gamma variable with
Thus,
Its density is
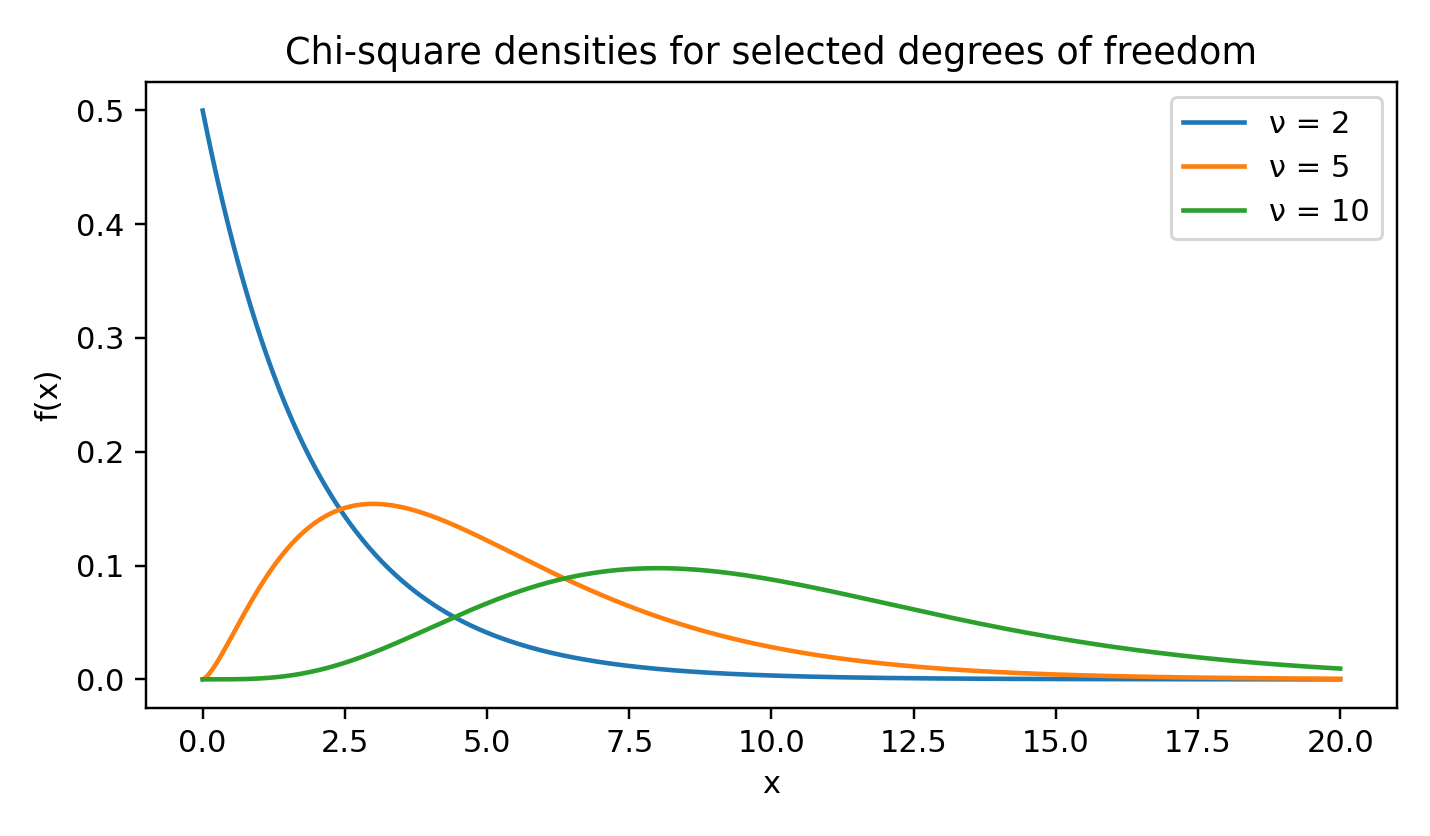
Chi-square probability density functions
The mean and variance are
If are independent standard normal variables, then
If are sampled independently from , then
This result underlies confidence intervals and hypothesis tests for a normal population variance.
Post-Test
- State the gamma density under the shape-rate parameterisation.
- If , find its mean and variance.
- Identify the exponential distribution as a gamma special case.
- If , find its mean and variance.
- If , express its distribution as chi-square.
- State the condition required for sums of independent gamma variables to remain gamma.
Selected answers: 2. and ; 4. and ; 5. ; 6. a common rate, or equivalently a common scale.